









Klump, a Nigerian buy-now-pay-later (BNPL) startup, has shut down after five years of operations, citing difficulties securing lending capital, lengthy integration processes and restrictions imposed by financial institutions, RaveNewsOnline reports.
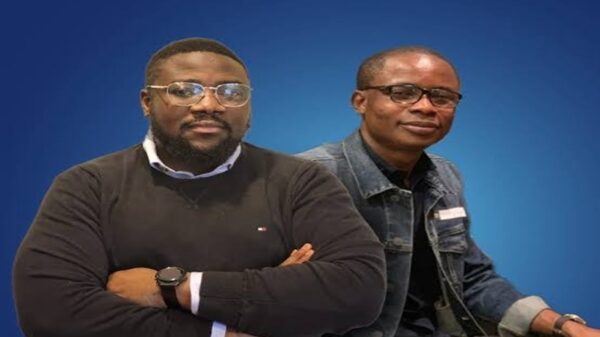
Celestine Omin and Olufunbi Falayi, Klump’s co-founders, announced the shutdown in a farewell note, explaining that they had weighed raising additional capital against selling the business before deciding to wind down operations.
Klump raised approximately $1.2 million across a seed round and an extension.
The company developed technology that allowed customers to pay for purchases in instalments while enabling merchants to offer financing at checkout.
The co-founders expressed disappointment over the decision to shut down the business but reflected on the satisfaction of building a product that customers eventually used.
“Today, with heavy hearts, we are announcing that Klump is shutting down. We are proud of what we built. Few things are as fulfilling as watching people use a product that once existed only in your imagination,” they said.
According to the founders, Klump initially operated its own loan book, allowing it to make lending decisions quickly and finance purchases that traditional lenders might not support.
This gave the company control over underwriting speed and loan sizes, but its plans to secure debt financing to fund further growth did not succeed.
The decision to close followed a reassessment of its business model, with the founders concluding that BNPL works better when embedded within a broader financial services platform.
Founded in 2021, Klump set out to make online shopping more accessible by allowing customers to purchase products immediately and spread payments across four instalments through its flagship product, Pay with Klump.
The platform also offered merchants a way to convert shoppers who might otherwise abandon their carts because of the upfront cost of purchases.
However, the experience of building a dedicated BNPL business exposed the limitations of operating in a market where consumer credit depends heavily on access to financing and partnerships with established lenders.
After struggling to secure debt financing, Klump moved towards a platform-based model that connected shoppers with financial institutions capable of providing credit.
Under the arrangement, participating lenders assessed applications, funded purchases and assumed the associated credit risk, while Klump provided the technology connecting customers, merchants and lenders.
Its lending partners included First Bank, Credit Direct, Stanbic IBTC, Polaris Bank, Wema Bank, Fidelity Bank and RenMoney.
The shift reduced Klump’s direct exposure to loan defaults but created another challenge of dependence on financial institutions to integrate its technology, approve customers and provide credit at scale.
The founders said bank integrations could take between six and 18 months, with some taking close to three years to complete commercial and legal processes. Lenders also retained control over the sectors they financed, loan amounts and the risks they were willing to accept.
Earlier in 2026, the founders considered raising additional capital or pursuing a sale.
They eventually opted to explore an acquisition, but discussions with potential buyers did not produce an acceptable outcome.
Some interested fintech companies had not developed their lending operations sufficiently to absorb Klump, while other discussions failed to result in a suitable transaction.
The company eventually received an offer but declined it, without publicly disclosing the specific reasons.
According to reports, Klump had previously attracted acquisition interest in the fourth quarter of 2023, but that process also collapsed after months of due diligence.
Despite the challenges, Klump continued to pursue commercial expansion before its shutdown. A partnership with Jumia brought instalment-payment options to the e-commerce marketplace.